The Supreme Court's NEEPCO v Astra Construction ruling confirms a contractual interest bar can strip pre-reference interest from arbitral awards, turn


insghits
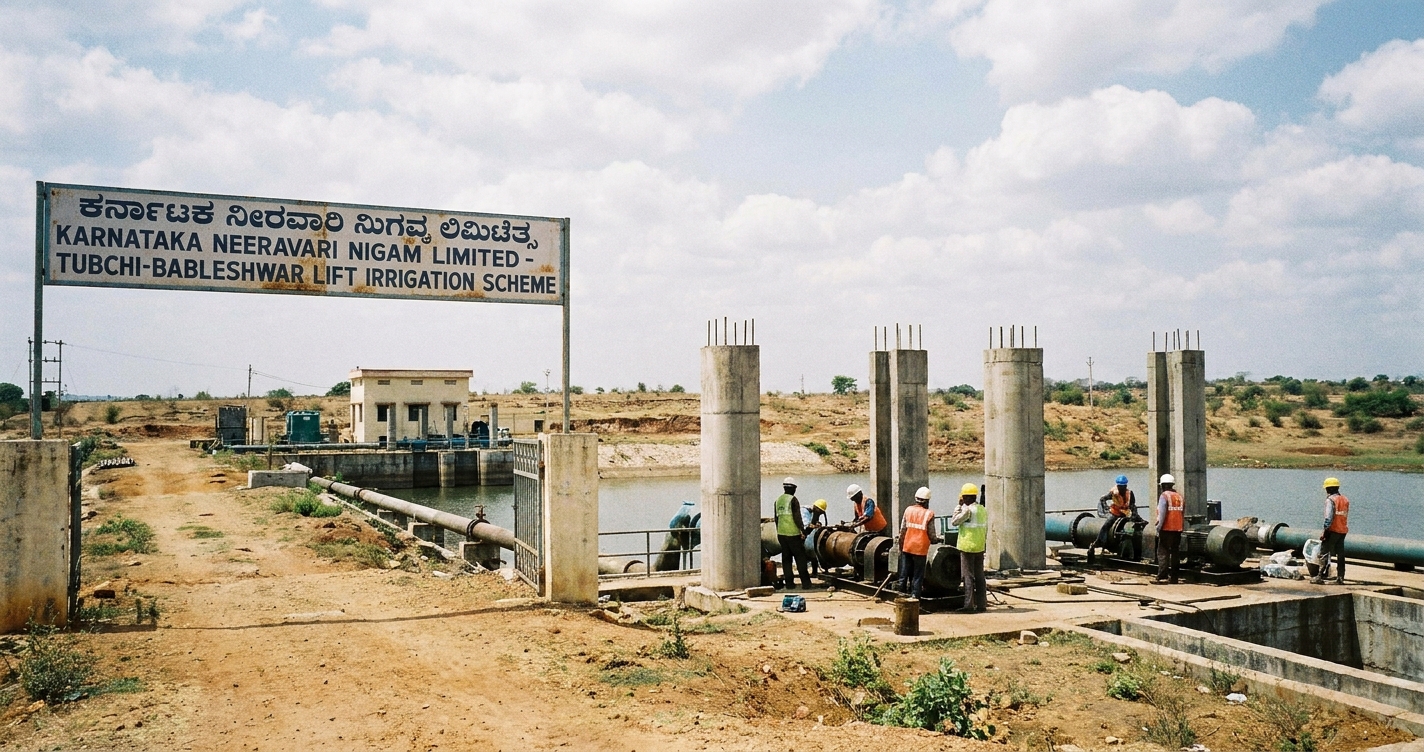
The Karnataka High Court has quashed a ₹71.52 crore service tax demand against the IVRCL–DRN Infra joint venture, holding that the sale-of-goods component of a lift irrigation works contract is not a taxable service.
Justice S.R. Krishna Kumar's order protects the commercial structure of turnkey irrigation packages awarded by Karnataka Neeravari Nigam Limited (KNNL).
The dispute arose from the Tubchi-Bableshwar lift irrigation project, which KNNL awarded to the IVRCL–DRN Infra JV on a turnkey basis, covering design and construction of civil works — intake forebay, pump house and electrical works — plus five years of operation and maintenance.
Revenue built its case from Form 26AS and income-tax data for FY2015-16 and FY2016-17, issuing a show-cause notice in April 2021.
The Court rejected that approach: the Service Tax (Determination of Value) Rules, 2006 require the goods element to be excluded before service tax is computed; the Supreme Court's BSNL ruling preserves the goods-services split.
The Court identified two structural protections.
1. Governmental authority status. KNNL qualifies as a governmental authority under Notification No. 25/2012-ST. The lift irrigation works serve Article 243W functions — water supply and planning for economic and social development — and therefore fall within the exemption for irrigation works executed for the government.
2. Extended limitation cannot rest on Form 26AS entries alone. Under Section 73, suppression must be a deliberate act intended to evade tax; an omission cannot automatically become suppression where facts were known to the department, and Revenue bears the burden of proof.
For the IVRCL–DRN Infra JV, the ruling removes a ₹71.52 crore contingent liability on a single irrigation package.
For the wider market, indirect tax exposure on turnkey irrigation works is governed by the goods-versus-services split, not the contract label.
The KNNL governmental-authority finding is a bid-stage structuring template for contractors executing lift irrigation and pump house packages for state undertakings.
The companion ruling in Asian Infra's case extends the same logic to submersible pump suppliers under the Ganga Kalyana scheme whose VAT-paid sales were reclassified as services.
The operational signal: tax risk in irrigation EPC is a documentation and structuring problem, not an unavoidable cost. Protection holds only where goods and service components are separately invoiced and reconciled across VAT, service tax and Form 26AS records.
Insights
The Supreme Court's NEEPCO v Astra Construction ruling confirms a contractual interest bar can strip pre-reference interest from arbitral awards, turn
NHAI and Sardar Sarovar Narmada Nigam Limited have signed a time-bound framework for National Highway, canal and pipeline crossings in Gujarat, waivin
A four-day SIB operation near Banaras Locomotive Works has put ₹4.25 crore of GST evasion on record — and turned scrutiny on the composite civil-works


Powered by

© Tuskus 2025 - All Rights Reserved by Teamic Creative Lab Pvt. Ltd.
