More than 800 objections hit the Greater Bengaluru Authority within five days of a notice proposing the removal of 1,128 trees for the Hebbal tunnel.


insghits
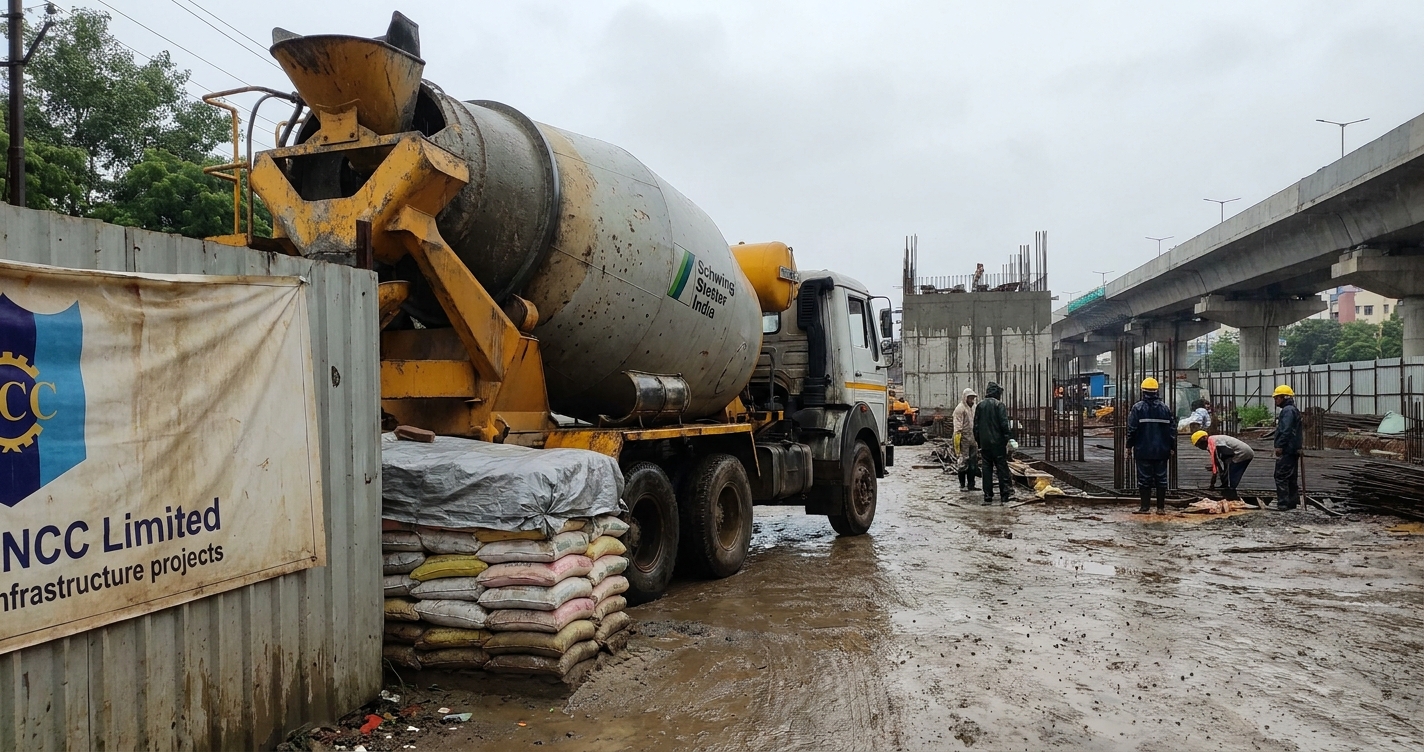
The July building-material picture from Equirus Capital is a study in two time horizons.
Near-term, monsoon rains kept construction subdued, dealer offtake thin and cement procurement need-based. Medium-term, public capital expenditure by the Centre, states and CPSEs rose 19% year-on-year in April-May 2026—the strongest anchor available for a FY27 demand recovery.
That divergence is visible in pricing behaviour. Cement prices stayed flat to slightly lower across most markets, falling about ₹5 per bag in western and central India and rising ₹8 per bag only in Hyderabad.
Equirus reads the mills' price hikes as largely defensive and hard to sustain while demand is weak and new capacity is coming onstream. The commercial implication is blunt: producers are protecting margins, not chasing volume or price leadership, with H1 FY27 volume growth expected to stay sluggish.
Yet the execution side is already positioning:
- Schwing Stetter India is committing about ₹400 crore to capacity expansion and a greenfield unit, a direct bet on medium-term infrastructure demand.
- NCC booked ₹1,052.71 crore in fresh July orders—₹590.38 crore from buildings and ₹462.33 crore from water projects—signalling that order flows remain positive despite seasonal execution slowdowns.
- India's core infrastructure index rose 5% year-on-year in June, its strongest reading in five months, led by cement, electricity and iron ore output.
The overlooked signal sits in capital markets. Building-material M&A was nil in July 2026 and remains nil for CY26; the last major transaction cited is Asian Paints' acquisition of 40% of Obgenix Software for ₹186.7 crore in CY25.
ECM activity is also blank for the year—the last deals referenced are the ₹451.3 crore Euro Pratik IPO and a prior KEI QIP. Private equity is muted at three CY26 deals, the largest being AllHome's ₹200 crore raise from Bessemer Venture Partners.
The public-capex-led demand story has not yet translated into listed-market capital formation in building materials.
For contractors and equipment suppliers, the read is clearer:
The FY27 upcycle is being underwritten by government balance sheets, not private capital.
Producers who carry balance-sheet strength through H1 FY27 margin compression will be positioned to capture the volume recovery. Those betting on price-led earnings before demand firms risk ceding share in a market that still leans heavily on the unorganised sector.
Insights
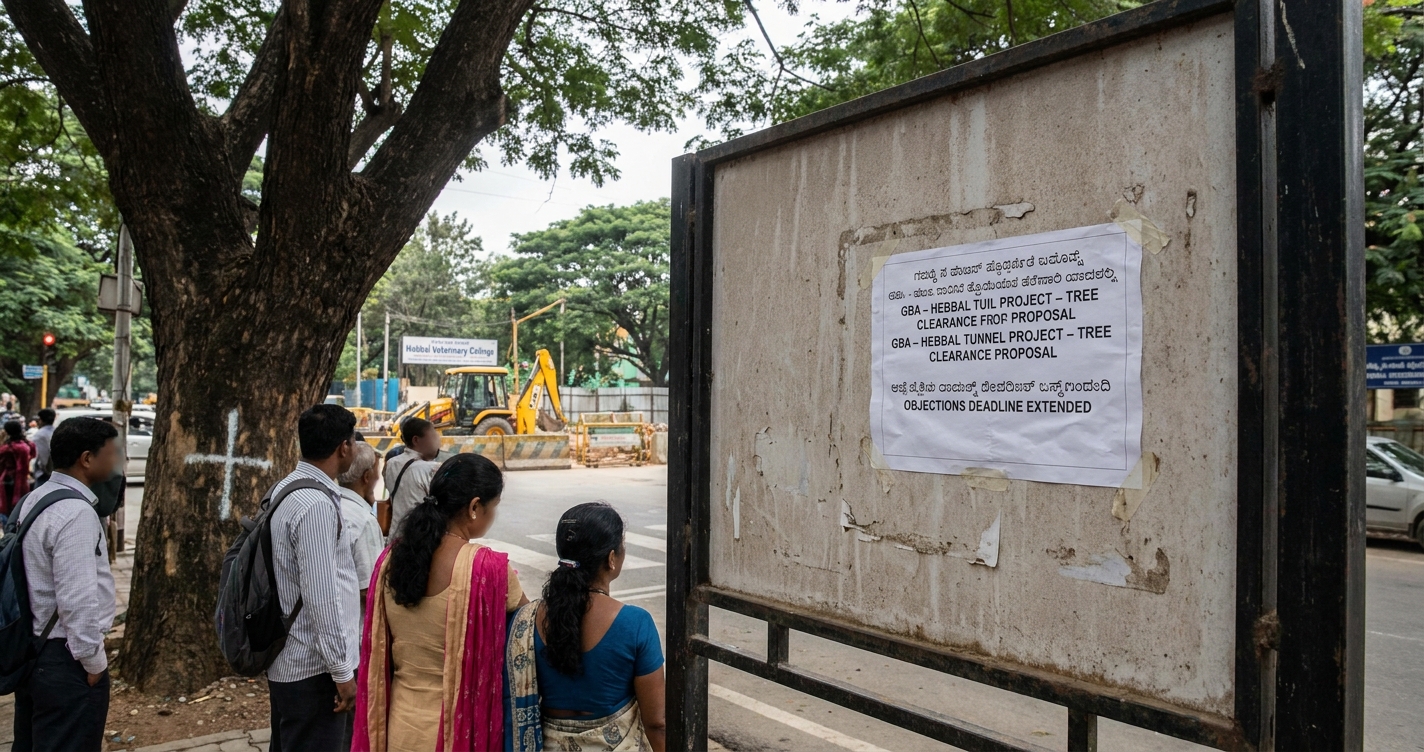
More than 800 objections hit the Greater Bengaluru Authority within five days of a notice proposing the removal of 1,128 trees for the Hebbal tunnel.
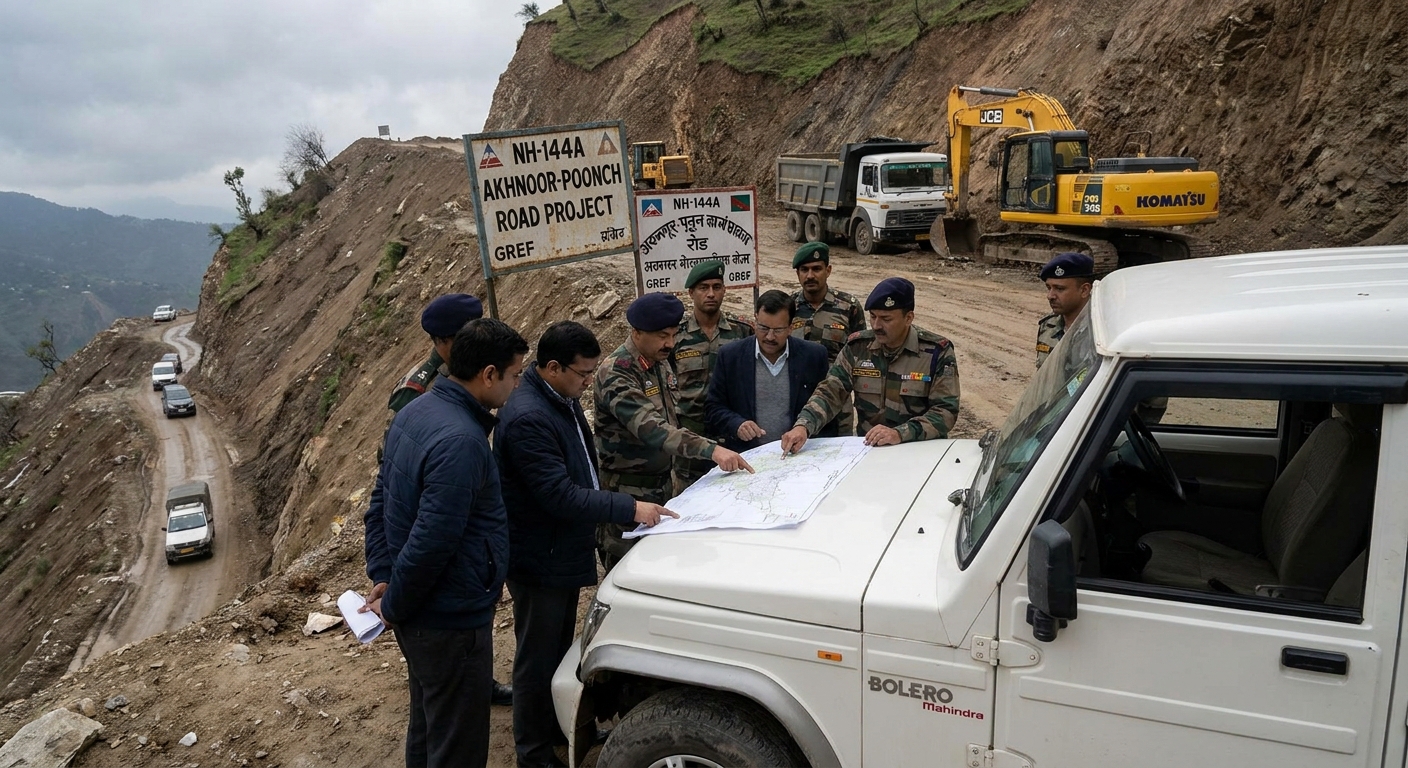
Deputy Commissioner Poonch Ashok Kumar Sharma chaired a September 25 review of bottlenecks on National Highway-144A, the strategic Akhnoor–Poonch corr
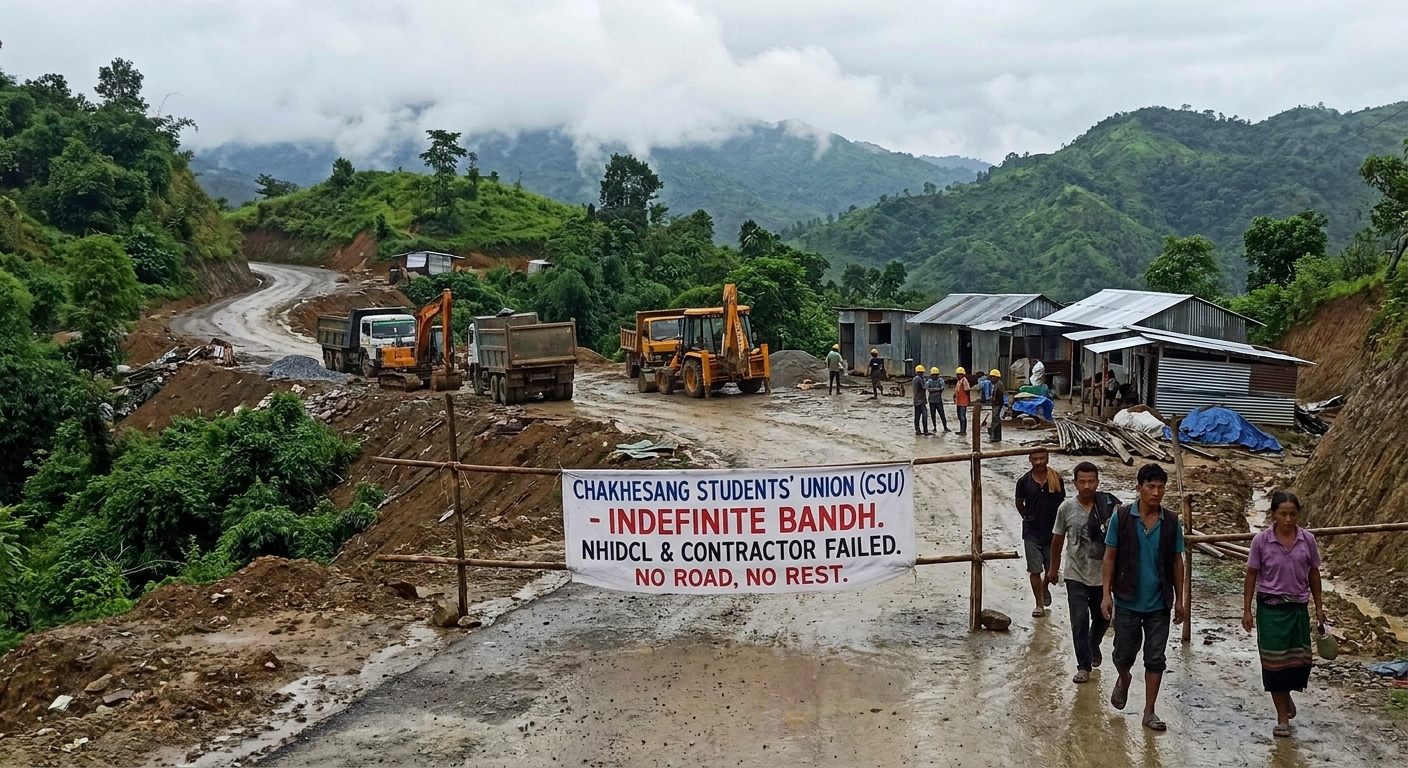
The Chakhesang Students Union has given NHIDCL 72 hours to terminate the contractor on the Chakhabama-Kikruma package of NH-29, with 44.30% physical p


Powered by

© Tuskus 2025 - All Rights Reserved by Teamic Creative Lab Pvt. Ltd.
