RITES' 58% repricing of the Bidar–Kalaburagi electrification mandate shows how cost-plus turnkey contracting shifts escalation risk from consultant to


insghits
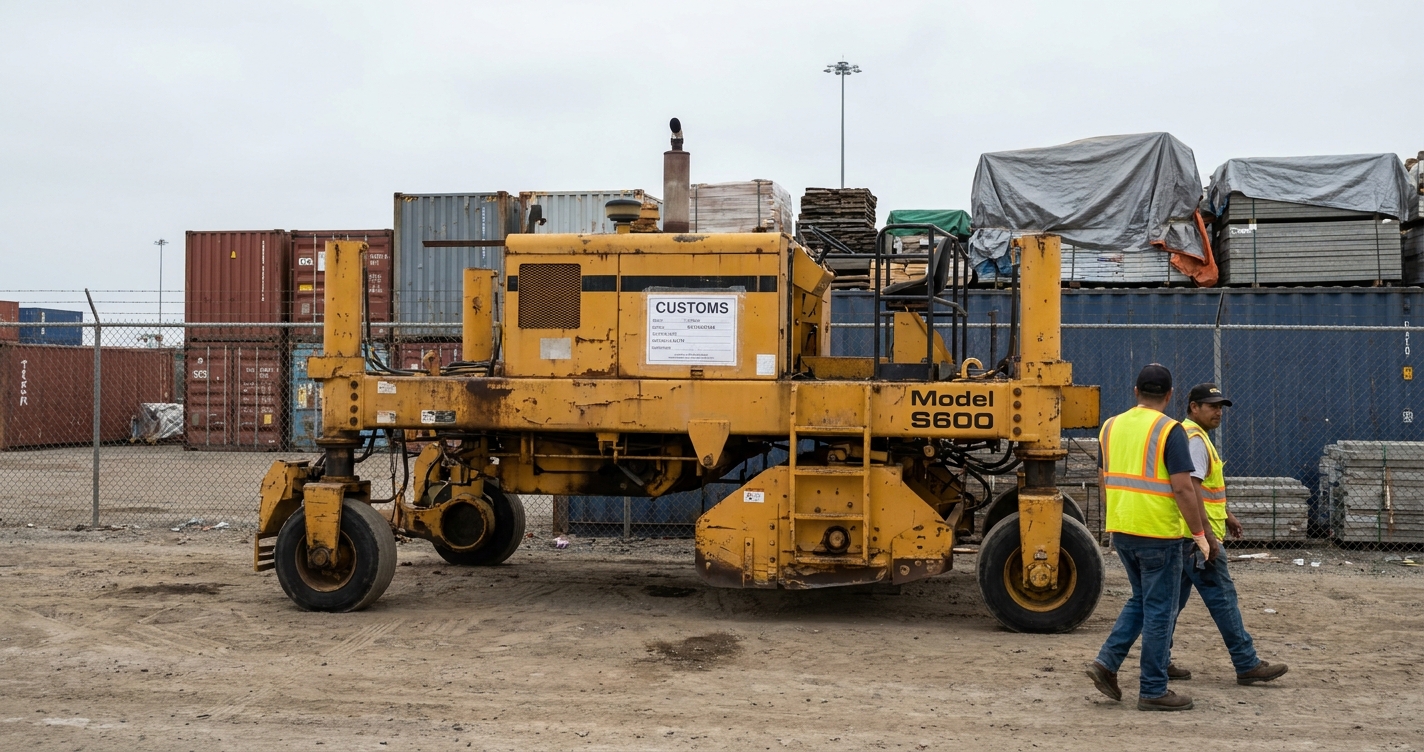
For highway contractors, the true cost of a slipform paver finisher is not the purchase price alone. It is the price plus the customs exposure attached to the machine for the duration of the exemption lock-in. CESTAT Mumbai has now drawn that line more precisely.
The bench of Ajay Sharma and C.J. Mathew set aside a ₹1.32 crore customs duty recovery, confiscation of a Model S600 slipform paver finisher, and all consequential penalties, ruling that cancellation of the underlying road contract did not automatically extinguish the importer's entitlement under Serial No. 230 of Notification No. 21/2002-Customs.
The machine, valued at ₹5.55 crore, was imported in December 2010 for a 77.80 km two-lane concrete pavement project on National Highway 21. The project was awarded by the Public Works Department of the Government of Chhattisgarh in June 2010.
It cleared Jawaharlal Nehru Customs House at Nhava Sheva, then idled in Mumbai when work could not commence due to Maoist disturbances. The contract was terminated on July 8, 2011. Customs seized the machine on October 4, 2011 — barely a year into a lock-in running to December 2015.
The department argued the machine was never deployed, so the exemption failed. The Tribunal rejected that logic, separating threshold eligibility at import from continuing eligibility during the lock-in.
A validly obtained exemption is not retrospectively destroyed by a later contract breakdown.
Non-use, absent evidence of diversion to an ineligible project, is not breach.
Commercially, the ruling matters three ways.
- Protects the capital model behind mechanised concrete paving — contractors who import specialised equipment under duty concessions do not forfeit them when force majeure or termination stalls deployment.
- Penalises premature seizure — the Tribunal excluded the period from seizure onward, recognising the department's own action created the non-compliance it alleged.
- Disciplines suspicion-based adjudication — the order's focus on the importer's 'character and behaviour' was dismissed as 'proverbial straw clutching.'
For the importer represented by Dr. Sujay Kantawala, the relief is concrete: restoration of the machinery, the show-cause notice set aside, and liberty to approach customs for termination of the deferred exemption with depreciation independently determined.
Gulshan Chopra, who faced ₹10 lakh penalties under Sections 112 and 114AA, is cleared alongside the importer.
The operational lesson is documentation. The ruling turns on what can be proven: the contract award, the authority's certification, the absence of diversion, and the impossibility of deployment.
In disturbed corridors like Chhattisgarh's NH-21 — a Left Wing Extremism-affected belt — the gap between award and execution can be fatal to cash flow if customs exposure is layered on top. The exemption survives; the contractor's job is to build the evidentiary record that defends it.
Insights
RITES' 58% repricing of the Bidar–Kalaburagi electrification mandate shows how cost-plus turnkey contracting shifts escalation risk from consultant to
NHAI's 21 September 2026 design guidelines lock uniform 60-70m right-of-way and structure standards for 4-lane and 6-lane high-speed corridors, reshap
Hazoor Multi Projects' Rs 200-crore NHAI award in Tamil Nadu is a user fee collection and maintenance mandate, not a construction order — and that dis


Powered by

© Tuskus 2025 - All Rights Reserved by Teamic Creative Lab Pvt. Ltd.
