IRB Infrastructure Developers' Q2FY27 net profit rose 84.85% to ₹260.15 crore on 15% toll revenue growth and higher InvIT distributions.


insghits
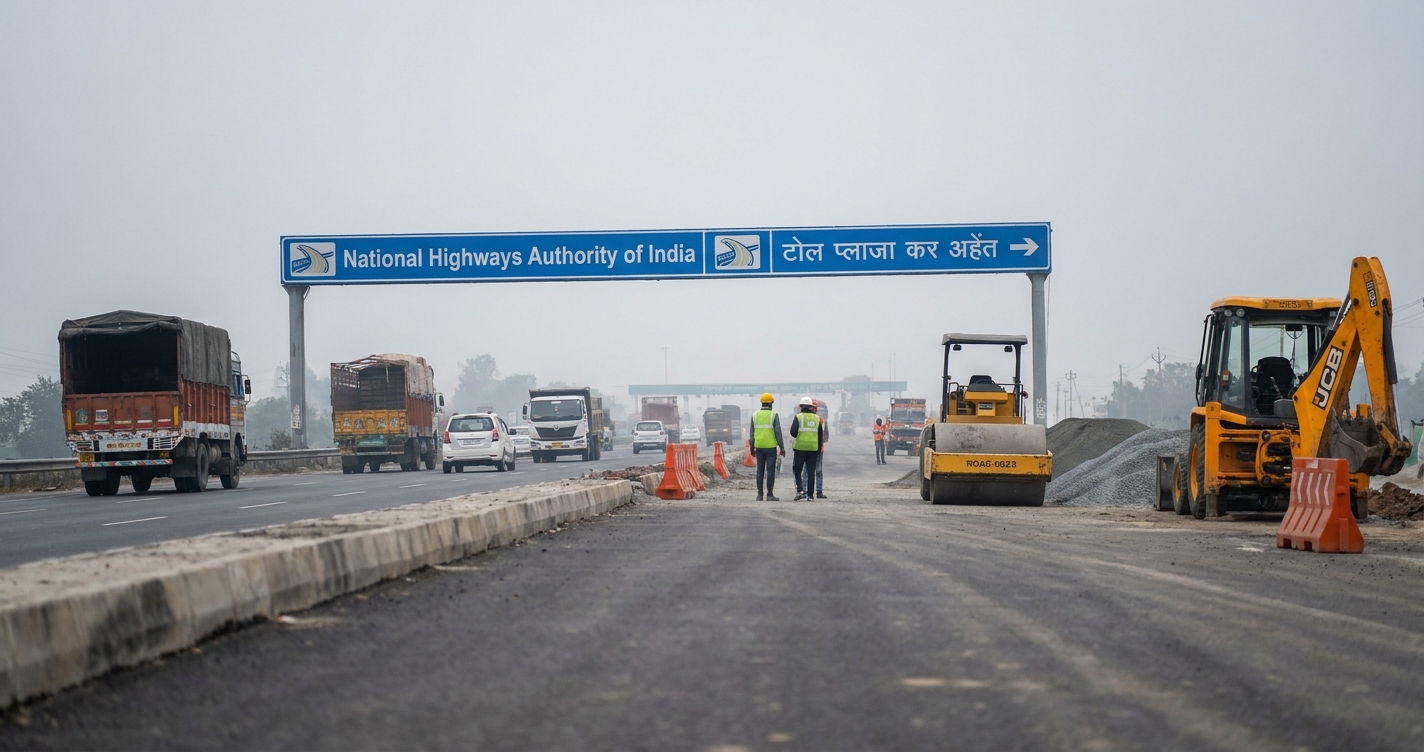
NHAI approved 910.76 km of highway transfers to Raajmarg Infra Investment Trust on 22 October. That is 80% of its FY27 monetisation pipeline moving through a channel where no price has been disclosed.
The Ministry of Road Transport and Highways signalled the InvIT preference in February 2025. Twenty months later the structure is live, and the National Highways Authority of India is simultaneously seller, approver and part-owner.
It holds 15% of Raajmarg's units and 10% of National Highway Infra Trust, which takes the remaining 450 km in its sixth acquisition round.
Read the retained holding carefully. NHAI keeps toll revenue beta while booking proceeds against debt that has already fallen to below Rs 2 lakh crore from Rs 3.42 lakh crore at end-FY23.
The roads were selected from 17 operating stretches totalling 1,692 km. Uttar Pradesh carries 429.3 km of the Raajmarg list, the heaviest single exposure across seven states.
Raajmarg's investment manager has not yet reviewed the list. Pricing is unresolved.
This is the procurement consequence nobody has priced. Toll-operate-transfer existed to make the market tell NHAI what a completed corridor was worth.
Bundle 19 in Tamil Nadu, 184.5 km for Rs 2,259 crore, closed in July as the year's first ToT deal. Bundles 20, 21 and 22 remain open.
Those bidders are now competing for stretches that sit behind a 1,360 km preferred list. Bidder aggression falls when the asset pool thins and the good corridors leave by negotiated transfer.
Retail capital is the second shift. Raajmarg is public, so NHAI's deleveraging now runs through household savings and InvIT unit yield pricing rather than institutional credit alone.
Against a Rs 30,000 crore annual target and one Rs 2,259 crore ToT close, the arithmetic depends on these transfers clearing at defensible valuations.
Watch two numbers:
- The undisclosed Raajmarg price per km against the 260 km, Rs 9,500 crore debut
- Bid values on Bundles 20 to 22
If ToT bids soften, NHAI has swapped competitive discovery for captive placement and inherited the toll risk it meant to sell.
Insights
IRB Infrastructure Developers' Q2FY27 net profit rose 84.85% to ₹260.15 crore on 15% toll revenue growth and higher InvIT distributions.
IRB Infrastructure Developers' Q2FY27 net profit rose 84.85% to ₹260.15 crore on 15% toll revenue growth and higher InvIT distributions.
IRB Infrastructure Developers' Q2FY27 net profit rose 84.85% to ₹260.15 crore on 15% toll revenue growth and higher InvIT distributions.


Powered by

© Tuskus 2025 - All Rights Reserved by Teamic Creative Lab Pvt. Ltd.
